Featured

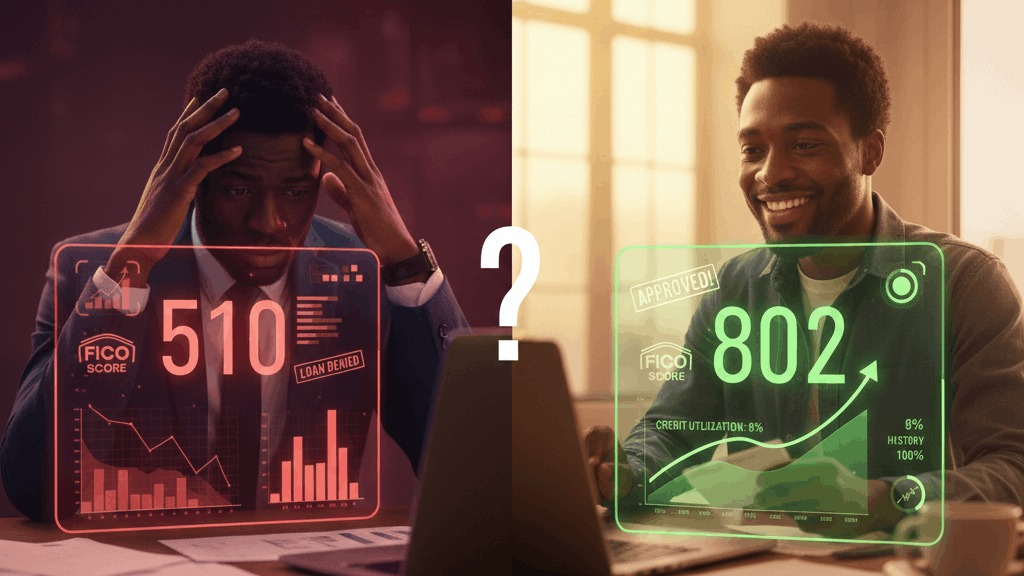
The Strategic Roadmap to Higher Credit Scores
Table of Contents
Revealing outcomes for "how" in what method or way; by what ways?. How did the mishap take place? How harmed is the automobile?
Essential Financial Education Tips for Successful ConsumersHow do you imply? If they do not have vanilla, how about chocolate? (used as an intensifier). How rarely I go there! by what title or name?. How does one address the president? at what price. How are the brand-new vehicles going, more affordable than in 2015's designs? by what amount or in what measure or quantity?.
How does the demon appear in the first act of the opera? How does the medication come? I do not care how you leave your desk when you go.
In whatever manner or way;. You can take a trip how you please. He informed us how he was honest and could be relied on.
Improving Key Financial Literacy Principles for Today's Adults
You haven't any desire to go? How come you never visit us any longer?/ ha/ Facetious: Often Offensive.
(intensifier) really much so! (as a toast) good health! Taped before 900; Middle English hou, ou, hu, Old English h; cognate with Old Frisian h, ho, Dutch hoe; similar to Old High German hweo, German wie, Gothic hwaiwa First recorded in 181020; of unsure origin Examples are offered to show real-world usage of words in context.
From Jul. 28, 2026 Warsh developed five job forces of outdoors experts to review the reserve bank analyzes the economy and interacts its decisions. From Jul. 28, 2026 But in his latest book, Levine shifts the focus from recognizing attachment styles to ask a various concern: do you end up being protect? From Jul.
Key Legal Rights Under 2026 Credit Laws
From Jul. 28, 2026 That's Dr. Edward Williams discovers Phineas almost thirty minutes after the mishap. From "Phineas Gage" by John Fleischman Longtime 'SportsCenter' anchor Shae Cornette has been named the brand-new of 'Very first Take,' ESPN's popular sports debate reveal starring Stephen A. Smith. From Nov. 19, 2025 "We have chosen to study in great information the and whys of why early birth impacts the developing brain," he states.
8, 2025 The are simpler to discuss than the whys when it comes to all this madness, so let's begin there. From "American Street" by Ibi Zoboi Definitions and idiom definitions from Unabridged, based on the Random House Unabridged Dictionary, Random House, Inc. 2023 Idioms from The American Heritage Idioms Dictionary copyright 2002, 2001, 1995 by Houghton Mifflin Harcourt Publishing Company.
Various types of credit report designs may determine your rating in a different way, however they generally think about payment history, amounts owed, length of credit rating, brand-new credit, and credit mix. Using for too much brand-new credit at when can momentarily lower your rating and might make lending institutions view you as a higher-risk borrower.
Ways to Raise Credit Scores Fast in 2026Inspecting your credit report frequently with the significant credit bureaus can assist you catch errors, spot potential identity theft, and conflict unreliable information. A good credit history can make it simpler to qualify for credit and might help you improve rate of interest on major purchases, such as a home or vehicle.
Comparing Credit Repair Versus Financial Methods
As a financial advisor, I have actually dealt with a great deal of individuals who have actually harmed their credit rating in one way or another due to the fact that they didn't understand the basics. The great news is that credit history can typically enhance with constant practices in time. Comprehending what affects your rating is the first step.
A credit rating is a mathematical expression of how credit-worthy you are. And a major aspect in that comes down to how likely you are to make your payments on time. It considers details from your credit report, consisting of credit card business you have actually dealt with, banks where you have or previously had loans, and practically anyone else who's considered you for credit.
You've probably heard of a FICO rating. That's because, while there are several companies that create credit rating, FICO scores are amongst the most commonly utilized. They range from 300 to 850, and each variety figures out how likely you are to get credit and at what interest rate. Your score not just can imply the difference between getting or not getting a home loan or vehicle loan, but also how much it will cost you to borrow that cash.
The typical credit rating is around 718. A rating of 760 or greater generally gets the best rates. Various credit rating like FICO or VantageScore use somewhat various techniques to calculate your rating. In general, your score is based on five factorshere are current FICO weightings: Your payment history (35%) How much you owe (30%) How long you've been using credit (15%) Number of new credit accounts and applications (10%) Types of credit you use (10%) Comprehending how all this fits together is necessary to addressing the next, maybe most crucial concern.
Your Legal Rights in 2026 Credit Laws
A bad credit rating may be due to some errors you have actually made, or it may be because you're brand-new to the credit world and don't have much to show for it yet. Whatever the reason, here are seven things you can do to bring that score upand keep it there.
Making routine, on-time payments is one of the best ways to bring it back up. That's what I did to improve my own score when I got out of college.
Preferably, the amount you borrow must be less than 30% of your offered credit line. This is called your credit utilization rate. If you have a card with a $5,000 limit, 30% of that is $1,500. But to me, the very best guide is to only charge what you can settle each monththat needs to be your real limitation.
This will assist you develop credit and, at the exact same time, avoid of financial obligation. New accounts and multiple credit applications can reduce your score and cause lending institutions to see you as a greater danger. Lots of cards offer rewards and discounts to draw you in, but don't be lured by totally free stuff.
How Expert Financial Guidance Boosts Your Score
That $10 off now might wind up costing you a great deal more later. And while it may seem counterintuitive, whenever you request a brand-new charge card, the lending institution will typically run a "tough questions" into your credit historyand credit questions can result in negative marks on your credit report.
Your credit mix matters. In addition to credit cards, having other kinds of credit such as student loans, a cars and truck loan, or a home loan can enhance your score. Avoid opening new accounts just to help your credit score. It's far better to develop the discipline of paying for debt and managing your existing credit wisely.
This includes accounts you no longer use and those with an absolutely no balance. As long as they're open, they will be factored into the typical age of your credit. You do not need to carry a balance to help your credit rating. However, a word of care here too: Do not be tempted to utilize a credit card just due to the fact that it's there.

Latest Posts

Locating No-Cost Credit Counseling Near Me in 2026
How to Find Free Financial Counseling in 2026
The Future of New Credit Repair Laws